Mineral deal financing brings together capital, mineral rights, technical evidence and commercial agreements to fund a mining opportunity. For brokers, the task is to structure a transaction that investors can assess, owners can accept and the project can realistically support. Across Africa, that means matching financing to the asset’s development stage while accounting for country-specific regulation, processing requirements and operating risks.
Consider an illustrative situation: a mine owner has a promising deposit, a buyer wants future production, and an investor has available capital. A deal appears within reach. Yet the buyer requires a product specification the proposed plant has never demonstrated, the investor expects security over rights that cannot simply be transferred, and the owner’s budget excludes the power connection.
The broker’s value lies in identifying and resolving those gaps before the parties commit.
Start With the Mandate and the Transaction
Before approaching funders, establish exactly what is being offered. Selling shares in a mining business, selling an asset, financing construction and arranging money for a mineral shipment are different transactions. Each requires its own assessment of ownership, repayment, liabilities and approvals.
A written mandate should identify the principal, confirm the signatory’s authority and define the broker’s role. It should address confidentiality, the permitted use of project information, exclusivity where agreed, the mandate period and compensation. Any non-circumvention provisions should be specific enough for legal advisers to assess their enforceability.
The fee agreement deserves particular attention. Define who pays, what amount the fee applies to, when it becomes payable and how phased funding is treated. A percentage of capital actually received produces a different obligation from a percentage of a headline facility that may never be fully drawn. Disclose competing interests and any compensation from another party.
Also establish whether the proposed activities require regulatory authorisation. Arranging investments or advising on shares can raise different requirements from introducing parties to a physical mineral sale. South Africa’s financial services regulator requires authorisation for regulated financial services; brokers should obtain advice on how the relevant rules apply to their precise role.
Match the Financing to the Asset’s Development Stage
An exploration prospect and an operating mine present fundamentally different investment propositions. Exploration funding pays to reduce uncertainty about the deposit. Construction funding pays to establish production. Working capital finances the period between spending money on operations and receiving payment from customers.
This distinction explains why an early-stage project may struggle to secure conventional project debt. Project finance relies primarily on the project’s future cash generation, while a new operation has no production revenue during construction. Geological promise alone does not establish a dependable repayment source.
A sensible financing strategy therefore identifies the next achievable milestone. The immediate requirement may be drilling, metallurgical testing or a feasibility study, rather than the entire mine development budget. Funding that milestone can provide the evidence needed to negotiate a larger transaction.
Build a Capital Stack the Project Can Support
The capital stack is the combination of funding sources and their respective rights to repayment, security and returns. It may include shareholder equity, senior loans, equipment finance, buyer prepayments, royalties or streaming arrangements.
These sources need to work together. A lender, equipment financier and buyer providing an advance may each seek rights over project assets or sale proceeds. Their agreements must establish priorities, permitted payments and what happens if the project defaults. These relationships are addressed through intercreditor arrangements and related financing documents.
The broker should compare the full economic burden of each proposal. Interest rates matter, but so do production discounts, security restrictions, fees, repayment timing and the portion of future revenue already committed.
Mineral Streaming and Royalty Financing
A mineral stream typically provides an upfront payment in exchange for the right to purchase an agreed portion of future metal production at a contractually determined price. Royalty financing generally exchanges upfront funding for a payment linked to an agreed revenue or production measure.
Both structures can raise capital without issuing additional shares. However, preserving the ownership percentage does not preserve all the project’s future economic value. A stream redirects part of the production benefit, while a royalty reduces the cash retained from the agreed payment base. Tax treatment and the interaction with other financing also require assessment.
For the broker, the practical questions concern duration, covered minerals, calculation methods, deductions, audit rights, buyback provisions and the effect on later fundraising. A seemingly attractive upfront payment can become expensive if it commits a valuable revenue stream for many years.
Phased Earn-In Agreements
An earn-in allows an investor to acquire an interest by meeting agreed obligations, such as funding exploration or completing defined development work. It can help owners attract technical expertise and capital without transferring the entire negotiated interest immediately.
The agreement should specify qualifying expenditure, deadlines, reporting standards, ownership earned at each stage and the consequences of withdrawal. It should also explain who controls the project during the earn-in and who owns the resulting technical data.
Earn-ins still transfer equity when the conditions are met. Their advantage is the ability to connect that transfer to delivered work and funding.
Make Off-Take Agreements Useful to Lenders
An off-take agreement commits a buyer to purchase mineral output under specified conditions. A credible agreement can strengthen the financing case by establishing a route to market. Lenders assess the buyer’s creditworthiness, contractual commitments and the reliability of forecast revenue alongside the project’s technical and financial position.
However, an off-take agreement does not automatically guarantee payment, a fixed selling price or a loan. The producer must still deliver compliant material, and the buyer must remain able and obliged to pay. A contract linked to market prices leaves the project exposed to price movements unless separate protection applies.
Brokers should examine product specifications, quantities, delivery schedules, pricing formulas, assay procedures, moisture adjustments, impurity penalties and payment terms. These details determine the revenue the mine can actually collect.
Where lenders seek security over contractual rights or receivables, legal advisers must confirm that the security can be validly created and enforced. Assignment restrictions, buyer consent, existing claims and local law can all affect the arrangement. A buyer’s expression of interest should never be presented as equivalent to an executed, financeable contract.
Validate the Geology, Title and Operating Assumptions
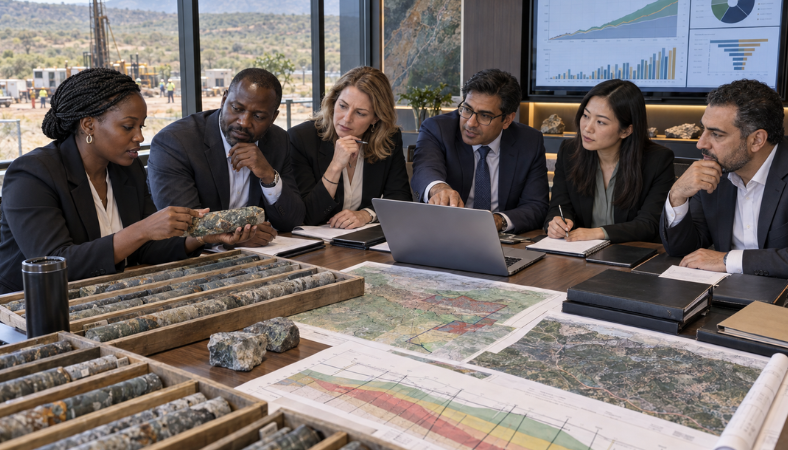
Technical due diligence begins with the evidence behind the project’s claims. Mineral resources are not the same as mineral reserves. Converting a resource into a reserve requires assessment of factors affecting economic extraction, including mining, processing, infrastructure, environmental and other relevant considerations.
Reporting frameworks also need accurate treatment. JORC is a public reporting code, while NI 43-101 governs scientific and technical disclosure for mineral projects under Canadian securities rules. NI 43-101 requires disclosure based on information from a qualified person and technical reports in specified circumstances. Neither label, by itself, guarantees financing or profitability.
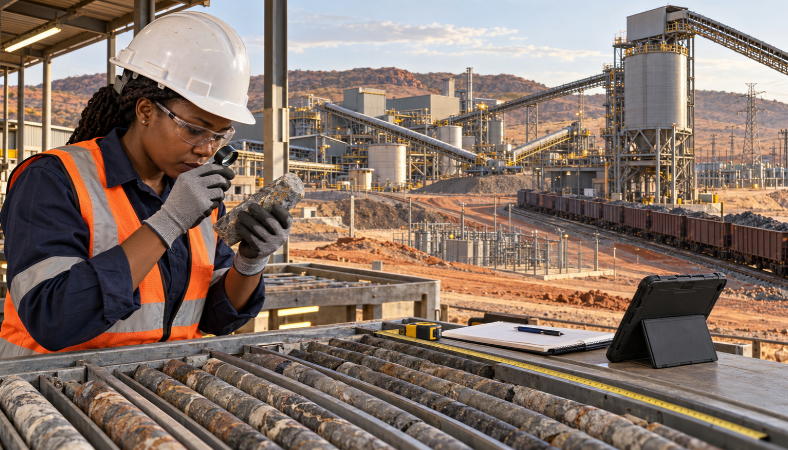
The broker should assemble a controlled data room containing the available geological reports, sampling records, metallurgical results, mine plans, cost estimates and production history. Independent specialists should assess material assumptions and identify missing work.
Legal review should verify the licence holder, covered minerals, boundaries, validity, renewal obligations, encumbrances and transfer requirements. A cadastre entry is a starting point; it should be checked against the underlying documents and current official records. Surface access, water permissions and environmental approvals require their own review.
Counterparty checks should establish beneficial ownership, signing authority, funding capacity and the source of funds. A compelling presentation cannot substitute for evidence that the parties can legally and financially perform their obligations.
Structure Joint Ventures Around Measurable Contributions
A joint venture can combine capital, operating expertise, mineral rights and local capabilities. The contributions should be documented and valued rather than assumed. A party offering land access must demonstrate the relevant rights; familiarity with local officials is not a substitute for regulatory approval.
The agreement should explain how budgets are approved, who appoints management, which decisions require consent and how additional funding is provided. It should also address cost overruns, a partner’s failure to contribute, dilution, distributions, disputes and exit rights. Clear shareholder arrangements are an important part of establishing a financeable project structure.
Pay particular attention to carried interests. The documents should explain whether another investor permanently bears the funding obligation or recovers those advances from future distributions. An ownership percentage means little without understanding the funding obligations and access to cash attached to it.
Apply Ownership Requirements Country by Country
African mining transactions cannot be structured around one continental ownership rule. Empowerment requirements, state participation, local procurement and community obligations are different concepts and may apply through different legal instruments.
In South Africa, official mining-right guidance links approval to financial and technical capacity, environmental requirements, social and labour provision and alignment with the Mining Charter. A transaction therefore needs a review of the applicable framework and the particular right, rather than an assumption that one ownership formula resolves every obligation.
Zimbabwe should not be described as imposing a blanket indigenous majority-ownership requirement across all mining investment. Its investment authority’s published mining guidance states that foreign investors may hold 100% shareholding in mining operations. The proposed activity, licences, transaction conditions and current law still require confirmation before closing.
The practical approach is to obtain a jurisdiction-specific legal assessment early enough for its findings to shape the funding and ownership structure.
Put Environmental and Community Obligations Into the Budget
Environmental, social and governance considerations affect how a project is designed, financed and operated. Applicable law establishes mandatory obligations, while lenders may impose additional standards through financing conditions. These should be identified separately.
International environmental and social performance standards cover matters including risk management, labour, resource efficiency, community safety, land acquisition, biodiversity and stakeholder engagement. Their application depends on the lender and project; they are not a single universal mining law.
For brokers, the commercial task is to ensure that agreed obligations have budgets, responsible parties and implementation dates. Water management, rehabilitation, closure, community commitments and monitoring cannot remain unfunded promises. The transaction model should also distinguish statutory royalties, contractual financing royalties and community payments so that none is overlooked or counted incorrectly.
Finance the Processing Route Required for Legal Sales
Beneficiation means processing minerals to improve their value or suitability for further use. Depending on the ore and intended product, it may involve concentration or more advanced treatment. It does not automatically require every mine to build a smelter.
Country requirements differ. Namibia introduced restrictions on exports of specified unprocessed critical minerals in 2023. A proposed transaction should verify the covered mineral, processing stage and any applicable permissions before assuming an export route is available.
Zimbabwe’s lithium export arrangements also demonstrate the importance of timing. In April 2026, authorities communicated concentrate export quotas and conditions for resumed shipments, including commitments to further local processing. A financing model should use the project’s confirmed export permissions and obligations rather than assume unrestricted sales throughout the loan period.
In the Democratic Republic of the Congo, the 2018 mining-law amendments require relevant rights holders to process minerals into marketable products domestically, either through their own facilities or approved processing entities. The law also provides a conditional route for exceptional processing abroad. This is more specific than a claim that every project must construct its own downstream plant.
The financing package should therefore reflect the actual processing solution. Compare an owned plant with a legally permitted toll-treatment arrangement, where a third party processes material for a fee. Assess recovery, available capacity, transport, power, water, waste handling and product acceptance before selecting either option.
Treat Infrastructure as Part of the Investment
A mine’s economic case depends on more than the deposit and processing equipment. Power supply, water access, roads, rail capacity and export facilities can determine whether production reaches a customer at a viable cost.
Where shared infrastructure involves public authorities and private investors, a public-private partnership may be an option. Such structures require coordinated contractual arrangements covering development, operation and financing. They are not automatically necessary or suitable for every mining project.
The broker should establish who funds each connection, who owns the infrastructure, what access is secured and how tariffs affect operating costs. A planned railway or proposed power line should not be treated as available capacity. Where infrastructure is critical, its delivery timetable and the consequences of delay belong in the financing negotiations.
An Illustrative Financing Test
Assume a hypothetical project requires US$15 million, including development costs, initial working capital and contingency. The proposed funding consists of US$6 million in equity, US$7 million in project debt and US$2 million in equipment finance. The sources match the budget, but that alone does not demonstrate affordability.
Suppose annual cash available for debt service is US$4.5 million after operating costs, taxes, working-capital movements and sustaining expenditure. Assume combined annual debt and equipment-finance payments total US$3 million. The debt service coverage ratio, calculated by dividing available cash by scheduled payments, is 1.50 times.
If weaker operating performance reduces available cash to US$3.3 million, coverage falls to 1.10 times. Now assume the project also incurs a contractual royalty of 2% on US$20 million of annual gross sales, excluded from the preceding cash figures. That additional US$400,000 payment reduces coverage to approximately 0.97 times, holding everything else constant and ignoring tax effects.
In that simplified scenario, annual cash generation no longer covers scheduled financing payments. The example is illustrative, not a market benchmark or recommended funding mix. It shows why brokers must test all funding obligations together and negotiate adequate protection against adverse outcomes.
Move From Agreement to Financial Close
Once the parties agree the commercial direction, a term sheet should set out the proposed economics, security, governance and conditions. It should clearly distinguish binding provisions from matters that remain subject to definitive agreements and approval.
The broker can coordinate the workstream, but technical specialists, legal advisers and financiers must complete their respective assessments. Outstanding issues should have named owners and deadlines. Material changes to the asset, budget or contractual structure should be disclosed before signing.
Signing documents and receiving usable funding are separate milestones. Drawdown may depend on equity contributions, regulatory consents, security registration, insurance, permits or other conditions. The broker’s closing process should track those requirements and confirm the agreed fee trigger.
Successful mineral deal financing connects a credible asset with an appropriate source of capital and a workable route to repayment or investment return. The strongest transactions make risks visible, allocate responsibilities clearly and leave the project with enough financial capacity to operate.
For readers exploring African mining assets, acquisitions or investment partnerships, the AFRINOMICS Deal Room provides a starting point for reviewing relevant opportunities and progressing discussions around a clearly defined transaction.